How I Built a Robinhood Chain Pons Volume-Making Bot
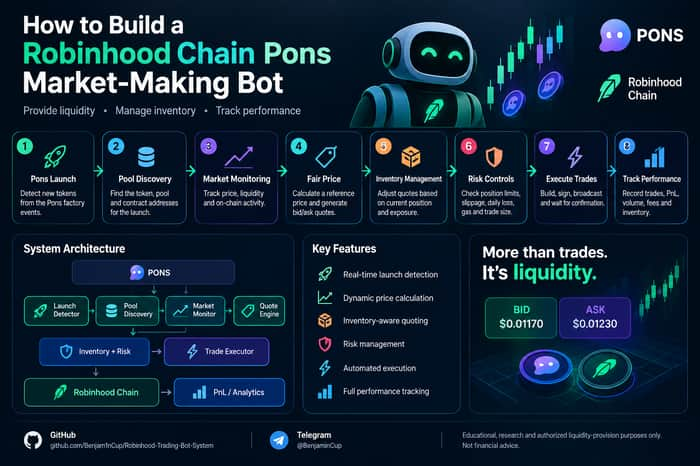
I've been experimenting with automated trading infrastructure on Robinhood Chain, and one interesting project is an educational market-making bot for Pons tokens.
The idea isn't simply to send buy and sell transactions.
A useful market-making system needs to continuously:
- Detect newly launched tokens
- Discover liquidity pools
- Monitor price and liquidity
- Calculate a reference price
- Generate bid/ask quotes
- Manage inventory
- Control slippage and risk
- Execute transactions
- Track PnL and execution costs
Here's the basic architecture I ended up with:
Token Launch
     ↓
Pool Discovery
     ↓
Market Monitor
     ↓
Fair Price
     ↓
Quote Engine
     ↓
Risk Check
     ↓
Trade Execution
     ↓
Inventory Update
     ↓
PnL / Analytics
Why Robinhood Chain?
One reason I like working with Robinhood Chain is that it's EVM-compatible.
That means familiar tooling such as Python, web3.py, smart contracts, RPC endpoints, and standard EVM transaction workflows can be used.
For example:
from web3 import Web3

w3 = Web3(
    Web3.HTTPProvider(RPC_URL)
)

if not w3.is_connected():
    raise RuntimeError("RPC connection failed")

print(w3.eth.chain_id)
The Robinhood Chain mainnet chain ID is 4663.
The important part isn't the connection itself. The interesting engineering starts after the bot can reliably observe the chain.
Detecting New Pons Markets
The first component watches the launch infrastructure for new tokens.
Conceptually:
Factory
   ↓
Launch Event
   ↓
Token Address
   ↓
Pool Discovery
   ↓
Market Registration
A market can then be registered internally:
launch = {
    "token": token_address,
    "pool": pool_address,
    "block": block_number
}
In production, contract addresses, event signatures, and ABIs should always be verified against the current protocol documentation rather than hard-coded from an old example.
Building a Simple Quote Engine
Once the bot knows where the liquidity is, it needs a reference price.
A basic starting point is a moving average:
def moving_average(prices):
    return sum(prices) / len(prices)
Then quotes can be generated around that price:
def generate_quotes(price, spread):
    bid = price * (1 - spread)
    ask = price * (1 + spread)

    return bid, ask
For example:
Fair price: $0.01200

Bid: $0.01170
Ask: $0.01230
This is intentionally simple.
A real market-making strategy could adjust the spread based on volatility, liquidity, inventory, trade flow, and execution costs.
Inventory Is the Hard Part
One of the biggest lessons from building trading systems is that execution is only half the problem.
Inventory matters.
If the bot accumulates too many tokens, it should reduce its willingness to buy and become more competitive on the sell side.
Inventory too high
       ↓
Reduce BUY aggressiveness
Increase SELL competitiveness
If inventory becomes too low:
Inventory too low
       ↓
Increase BUY competitiveness
This creates an inventory-aware quoting system instead of a bot that blindly posts symmetrical prices.
Risk Controls
Before sending a transaction, the bot should check several limits:
Maximum position
Maximum trade size
Maximum slippage
Maximum daily loss
Maximum gas cost
For example:
MAX_POSITION = 10000
MAX_TRADE_SIZE = 500
MAX_SLIPPAGE = 0.02
MAX_DAILY_LOSS = 100
If a trade violates one of these limits, the execution engine should reject it.
This is especially important for newly launched tokens where liquidity can change very quickly.
Transaction Execution
The execution pipeline looks like:
Generate Quote
      ↓
Risk Check
      ↓
Build Transaction
      ↓
Sign
      ↓
Broadcast
      ↓
Wait for Receipt
      ↓
Reconcile State
With web3.py:
receipt = w3.eth.wait_for_transaction_receipt(tx_hash)

if receipt.status == 1:
    print("Trade confirmed")
One important design decision is to separate transaction submission from portfolio accounting.
A transaction being broadcast doesn't necessarily mean the trade happened successfully.
The system should reconcile the actual blockchain receipt and update its internal state afterward.
Measuring Whether It Actually Works
A trading bot can look profitable until you include all the costs.
I track things such as:
Trade count
Buy volume
Sell volume
Average execution price
Slippage
Gas
Inventory
Realized PnL
Unrealized PnL
This gives a much better picture of whether the strategy is actually generating value.
For me, this analytics layer is just as important as the trading logic itself.
What I'd Build Next
The simple architecture above is enough to demonstrate the concept, but there are several areas I'd improve for a production system:
- Dynamic spreads based on volatility and liquidity
- Inventory skew to automatically rebalance exposure
- Real-time pool monitoring
- Better price discovery
- Transaction simulation before execution
- Automatic circuit breakers
- Persistent trade and PnL storage
- Monitoring dashboard and alerts
The architecture would eventually look like:
                  Pons
                   │
                   ▼
            Launch Detector
                   │
                   ▼
             Pool Discovery
                   │
                   ▼
             Market Monitor
                   │
                   ▼
              Quote Engine
                   │
                   ▼
           Inventory + Risk
                   │
                   ▼
            Trade Executor
                   │
                   ▼
          Robinhood Chain
                   │
                   ▼
             Analytics
What I Learned
The biggest takeaway is that market making isn't really about generating transactions.
It's a systems problem.
You need to combine:
- Blockchain infrastructure
- Market data
- Pricing logic
- Inventory management
- Transaction execution
- Risk controls
- Analytics
The trading strategy itself can be relatively simple. The difficult part is making the entire system reliable when market conditions change.
I'm continuing to experiment with automated trading infrastructure on Robinhood Chain and documenting what I learn along the way.
Open Source
I've also put together a broader repository with Robinhood Chain trading infrastructure and experiments:
Robinhood Trading Bot System — GitHub
For development discussions and collaboration:
[Telegram — @BenjaminCup](https://t.me/BenjaminCup?utm_source=chatgpt.com)
