Tax Credit vs Tax Deduction: Key Differences That Can Maximize Your Tax Savings
Introduction
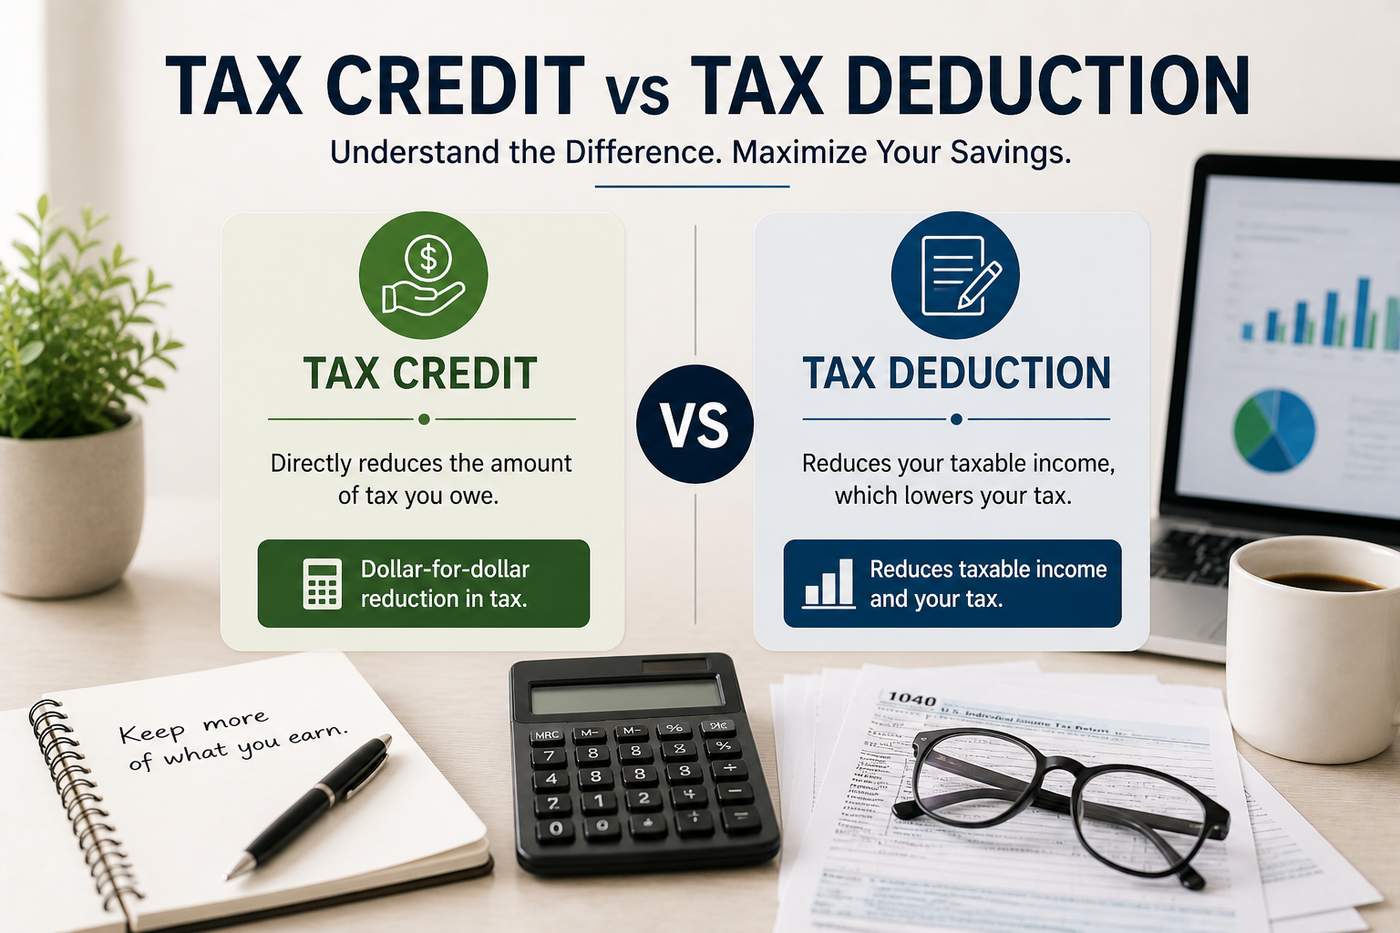
Understanding the difference between a Tax Credit and a Tax Deduction is fundamental to effective tax planning. Both reduce your tax burden. But they do it in very different ways. One lowers your taxable income. The other directly reduces the tax you owe.
Simple concept. Big impact.
In the broader framework of US Taxation, knowing how to use these tools correctly can significantly improve financial outcomes.
What is a Tax Credit
A Tax Credit is a direct reduction in the amount of tax you owe. It is powerful. If you owe $2,000 in taxes and receive a $500 credit, your liability drops to $1,500.
There are two main types: refundable and non-refundable. Refundable credits can result in a refund even if your tax liability is zero. Non-refundable credits, on the other hand, only reduce your tax to zero but do not provide additional refunds.
This direct impact makes tax credits highly valuable.
What is a Tax Deduction
A Tax Deduction reduces your taxable income rather than your tax bill directly. For example, if your income is $50,000 and you claim a $5,000 deduction, you are taxed on $45,000 instead.
The actual savings depend on your tax bracket. Higher income levels often benefit more from deductions because they reduce income taxed at higher rates.
Indirect effect. Still valuable.
Key Differences: Tax Credit vs Tax Deduction
The distinction between Tax Credit vs Tax Deduction lies in how they influence your tax calculation.
A Tax Credit reduces the final tax bill. A Tax Deduction reduces the income on which the tax is calculated. This difference may seem small, but the financial outcome can vary significantly.
Credits generally offer greater savings compared to deductions of the same value. That’s why understanding their role is essential.
Types of Tax Credits and Deductions
Tax systems include a variety of credits and deductions designed to support different financial situations.
Common tax credits include education credits, child-related credits, and energy efficiency credits. These directly reduce tax liability.
On the other hand, deductions may include mortgage interest, medical expenses, and charitable contributions. These reduce taxable income.
Both play important roles within US Taxation.
How They Impact Your Tax Liability
The impact of a Tax Credit is immediate. It lowers your tax bill dollar for dollar. A Tax Deduction, however, provides savings based on your tax rate.
For example, a $1,000 deduction may save $200 if you are in the 20% tax bracket. A $1,000 credit saves the full $1,000.
Clear difference. Strong effect.
Understanding this helps taxpayers prioritize which benefits to claim.
Choosing Between Tax Credits and Deductions
In most cases, taxpayers do not choose between a credit and a deduction for the same expense. Instead, they utilize all available options.
However, when a choice exists, credits are generally more beneficial. They provide direct savings.
That said, eligibility criteria must be carefully reviewed. Not everyone qualifies for every benefit.
Importance in US Taxation
Both Tax Credit and Tax Deduction are essential components of US Taxation. They are designed to reduce financial burden and encourage specific behaviors such as education, home ownership, and charitable giving.
They also make the tax system more flexible. Different taxpayers benefit in different ways depending on their financial situation.
Understanding these tools is key to effective tax management.
Relevance for NRIs and Cross-Border Taxpayers
For individuals managing tax filling for NRIs in USA, the use of credits and deductions becomes more complex. Cross-border income, foreign tax credits, and dual taxation rules must be considered.
NRIs may qualify for certain credits or deductions, but eligibility depends on residency status and income sources.
Professional guidance is often necessary to navigate these complexities and ensure compliance.
Common Mistakes to Avoid
One common mistake is confusing deductions with credits. This leads to incorrect expectations about tax savings.
Another issue is failing to claim eligible benefits due to lack of awareness. Many taxpayers leave money on the table simply because they do not understand what they qualify for.
Errors in calculation or documentation can also create problems during tax filing.
Avoid assumptions. Verify everything.
Strategic Tax Planning Tips
Effective tax planning involves maximizing both Tax Credit and Tax Deduction opportunities. Keeping track of eligible expenses, understanding qualification criteria, and planning financial activities in advance can improve outcomes.
For those dealing with tax filling for NRIs in USA, strategic planning is even more critical. It ensures compliance while optimizing tax liability.
Small decisions can lead to significant savings over time.
Conclusion
The comparison of Tax Credit vs Tax Deduction highlights a fundamental aspect of tax planning. While both reduce tax burden, they operate differently and offer varying levels of benefit.
In the context of US Taxation, understanding and applying these tools correctly can make a substantial difference. Whether reducing taxable income through a Tax Deduction or lowering tax liability directly with a Tax Credit, informed decisions lead to better financial outcomes.
For individuals, especially those handling tax filling for NRIs in USA, clarity and precision are essential. The right approach ensures compliance, minimizes errors, and maximizes savings.

