Why Home Sellers Are Pulling Their Listings Down in 2026
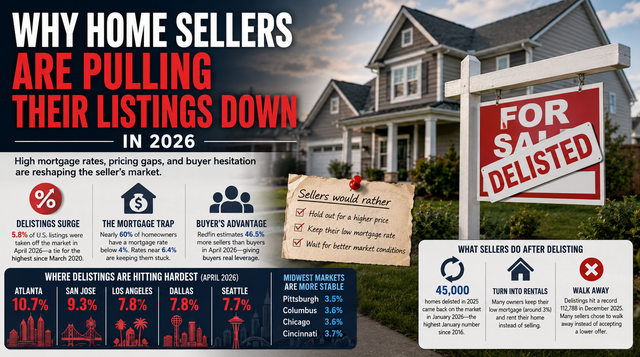
In April 2026, 5.8% of all U.S. home listings were taken off the market, according to Redfin. This was a tie with December 2025 for the highest delisting rate since the pandemic in March 2020. But back then, there was a clear reason. The entire country was shutting down, and the pandemic had frozen the housing market.
This time, there is no such crisis. Sellers are just pulling their listings instead of dropping the price. They ask for more than what buyers are willing to hand over.
Why Sellers Delist Instead of Cutting Prices
Delistings rose 3.8% month over month in April 2026, per Redfin's MLS data. That’s the second straight month they've climbed. The reason behind this is quite simple.
A lot of sellers locked their pricing expectations back in 2020 and 2021, when homes were selling in a few days and buyers were fighting each other just to get an offer accepted. Although the market conditions have shifted now, their price expectations haven’t.
Today's buyers are dealing with much higher monthly housing costs than they were three years ago. Mortgage rates averaged 6.33% in April 2026, per Redfin, so a price that made sense in 2021 doesn't work anymore at today's rate. Some sellers have adjusted. Redfin found that 60.5% of homes sold in April went for less than their original asking price. But plenty of others won't budge. They would rather pull off their listing instead of accepting an offer that low.
According to Realtor.com's November 2025 housing trends report, delistings in October were up nearly 45% year-to-date and about 37.9% compared to the year before, and that wasn't a one-month blip. Almost 6% of all active listings had been pulled every single month since June 2025, and the pace didn't let up. It kept climbing straight through the end of the year and into 2026.
For sellers who want to pull their property off the list or list it again, they can visit platforms like Houzeo to compare nearby listings. This helps them decide the correct course of action, whether to cut, relist, or walk away.
The Mortgage Trap That Is Keeping Sellers Stuck
Back in 2024, CFPB data showed nearly 60% of all active mortgages carried a rate below 4%. Many of those homeowners are still paying that same low rate today. Rates for a new mortgage, meanwhile, sit near 6.4%, almost double what they have now. So selling their homes and buying again elsewhere means giving up that low mortgage rate. For most people, that math doesn't make sense, so they stay put, even if they’d rather move.
Bankrate's numbers show just how deep that reluctance runs. In their 2025 survey, 54% of homeowners said there's no interest rate at which they'd feel comfortable selling this year. That's more than half the country effectively taking themselves off the market, not because they don't want to move, but because the numbers just don't add up in their favor anymore.
That reluctance is colliding with a market already tilted toward buyers. Redfin estimated 46.5% more sellers than buyers in April 2026, giving buyers real room to push back on price. Some sellers tested that market anyway, got offers too low, and pulled their listings. Others never listed at all.
Where the Delisting Wave Is Hitting Hardest
The problem is not spread evenly. Some cities are getting hit much harder. Atlanta had the highest delisting rate among the 50 biggest U.S. cities in April 2026 at 10.7%, followed by San Jose at 9.3%, with Los Angeles and Dallas each at 7.8% and Seattle at 7.7%.
Texas has taken one of the biggest overall hits. Houston reached 37 delistings for every 100 new listings by late 2025, peaking at 40 in August. California is dealing with its own version of the problem. Los Angeles recorded a ratio of 33, nearly as steep as Houston's. That delisting rate matters because it means sellers there aren't just taking a break and coming back. They're staying off the market for months.
The Midwest looks a bit different, though. Pittsburgh recorded just 3.5%, followed by Columbus, Chicago, and Cincinnati, all sitting between 3.6% and 3.7%. Buyers here are still competing actively. To find homes most suited to their needs, buyers often search for new homes for sale on platforms like Houzeo, Zillow, or Realtor.com.
What Sellers Do After Delisting
Not every homeowner who pulls a listing disappears forever. As per National Mortgage Professional, nearly 45,000 homes delisted in 2025 came back onto the market in January 2026. This is the highest January number in records since 2016, making up 3.6% of all homes on the market that month.
Others are skipping the sale entirely and turning their properties into rentals instead. That's especially true for owners sitting on a 3% mortgage who have no interest in giving it up for a new loan at 6.4%.
Delistings hit a record high of 112,788 in December 2025 alone, per Redfin. Behind that number are just as many owners who decided walking away was better than accepting less than the home was worth. Some of these sellers will come back with lower expectations. Others will just stay on the sidelines.
