US Tax Compliance Master Checklist for Foreign Owners
This is the master view of US tax compliance for foreign owners. The form list can feel overwhelming because the obligations layer onto each other based on what you own, where it sits, and what flows through it. The checklist below covers the core forms, the thresholds that trigger them, and how they interact so the calendar is clear before each deadline arrives.
Quick Answer
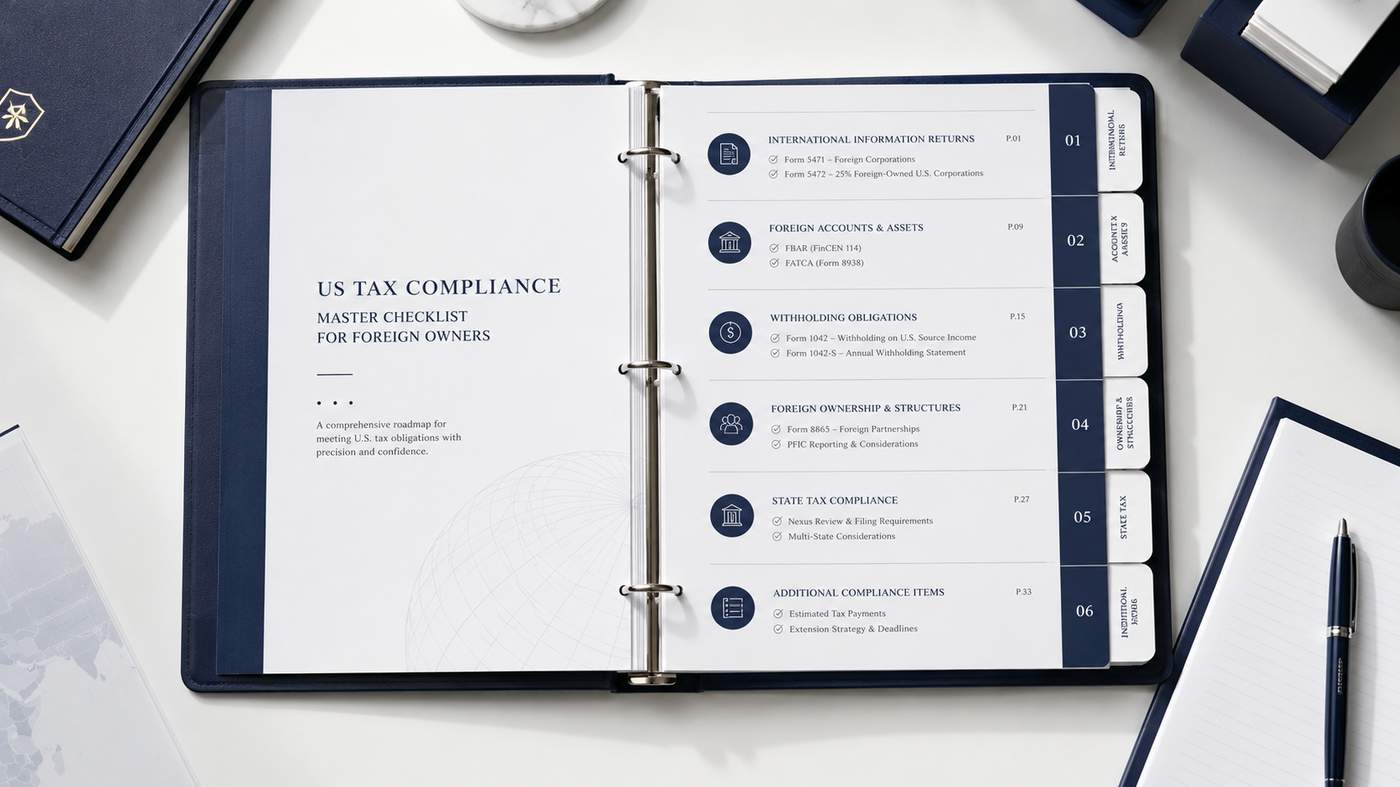
US tax compliance for foreign owners typically includes one or more of: Form 5471 for CFC ownership, Form 5472 for foreign-owned US entities with reportable transactions, Form 8865 for foreign partnerships, Form 8938 and FBAR for foreign financial assets above thresholds, Form 1042 plus 1042-S for US-source income paid to foreign persons, and state tax filings for any state with nexus. The exact combination depends on entity structure, ownership thresholds, and activity.
1. The Entity-Level Forms
These forms are filed by the US-side entity or by the controlling US shareholder, depending on entity type.
Form 1120 or Form 1065 are the underlying federal returns. Foreign-owned US entities still file the standard forms; the international information returns are attached. Our post on do foreign-owned US entities pay US tax covers the substantive tax positions that produce the numbers on these returns.
Form 1120: filed by US C-Corporations including foreign-owned ones, by April 15. Reports US-source and ECI on a worldwide basis for the corporation. Extensions to October 15 via Form 7004.
Form 1065: filed by US partnerships including foreign-owned ones, by March 15. Issues K-1s to partners. Extensions to September 15.
Form 1120-F: filed by foreign corporations with US-source income or US trade or business activity, by April 15 (June 15 if no US office). Reports ECI and FDAP.
2. Form 5472 for Foreign-Owned US LLCs and Corporations
Form 5472 is required for any 25%-or-more foreign-owned US corporation or any foreign-owned US disregarded entity (single-member LLC) that had reportable transactions with related parties during the year.
Reportable transactions: include capital contributions, loans, royalties, services, sales, rents, and most movements of value between the US entity and any related foreign party.
Filing requirement: one form per related foreign party. A US LLC owned by a single foreign owner who also lent the LLC money files at least one Form 5472, and may file more if multiple related parties had transactions.
Penalty: $25,000 per Form 5472 per year for non-filing. Continuation penalty up to $25,000 per 30-day period after IRS notice.
Our standalone post on Form 5472 filing requirements covers the related-party definition, reportable transactions, and the proforma 1120 requirement for disregarded entities.
3. Form 5471 for Controlled Foreign Corporations
Form 5471 is filed by US persons who control or hold significant interests in foreign corporations classified as CFCs. The form has multiple categories with different thresholds and information requirements.
Categories 1 through 5: covering different ownership levels and transaction types. Category 4 (control of a CFC during the year) and Category 5 (10%+ ownership of a CFC) are the most common for foreign founders with US operations.
Filing penalty: $10,000 per form per year base penalty under IRC Section 6038(b), with continuation penalty up to $50,000.
Statute of limitations: suspended on related items until the form is filed under IRC Section 6501(c)(8).
Coordination with GILTI and Subpart F: Form 5471 is the source of the inclusions reported on Form 8992 (GILTI) and the Subpart F schedules.
4. Form 8865 for Foreign Partnerships
Form 8865 is filed by US persons holding interests in foreign partnerships under IRC Sections 6038, 6038B, and 6046A. Four filing categories cover control, 10%+ ownership in US-controlled partnerships, contributions, and reportable changes.
Our standalone post on Form 8865 for foreign partnerships covers the four filing categories, the schedules required, and the catch-up procedures for prior-year gaps.
5. The Foreign Asset Reporting Forms
Form 8938: specified foreign financial assets above thresholds. For US residents, $50,000 end of year or $75,000 anytime ($100,000/$150,000 joint). For US non-residents, much higher thresholds. Filed with the federal return.
FBAR (FinCEN 114): foreign financial accounts above $10,000 in aggregate at any time during the year. Filed separately on the FinCEN site, due April 15 with automatic extension to October 15. Penalty $10,000 per non-willful violation, much higher for willful.
Form 8621: PFIC holdings, filed annually for each PFIC under IRC Section 1298(f). De minimis exception under Treasury Regulation 1.1298-1(c) for small holdings. No standalone monetary penalty but statute suspension under IRC Section 6501(c)(8).
Foreign-owner compliance gets complex fast. Most foreign founders need at least three of these forms in their first year of US operations. An international tax review maps the obligations to the structure.
6. Withholding Forms for US-Source Payments
If the foreign-owned US entity makes payments to foreign persons, withholding applies under IRC Sections 1441 and 1442 for FDAP income and Section 1445 for US real property dispositions.
Form 1042: annual return reporting amounts withheld on FDAP payments to foreign persons. Filed by the withholding agent by March 15, with extension to September 15.
Form 1042-S: issued to each foreign recipient of US-source income, summarizing the income and tax withheld. Filed with the IRS by March 15 and provided to the recipient by March 15.
Form W-8 series: received from foreign payees to certify non-US status and claim treaty benefits. The withholding agent retains these in records, does not file with the IRS.
Form 8804 and 8805: for partnerships with foreign partners and ECI, reporting Section 1446 withholding on the foreign partner's share of partnership ECI.
If your US entity has paid US-source income to foreign owners or contractors, the withholding mechanics, treaty rate reductions, and the $250 per-form penalty structure on Form 1042-S are summarized in our standalone post on FDAP withholding.
7. State Tax Compliance
State tax obligations apply alongside federal compliance and follow each state's own nexus and filing rules. Foreign owners often miss state filings because they think federal compliance is enough.
State income tax in any state with nexus from operations, employees, or significant inventory presence
State sales tax and use tax in states with economic nexus thresholds, typically based on revenue or transaction count
State franchise or annual report fees in formation states (Delaware franchise tax for entities formed in Delaware, California $800 minimum tax for entities doing business in California)
State-by-state nexus rules and the specific obligations in high-volume states are covered in our state tax compliance post for foreign-owned LLCs. The state analysis runs separately from federal and often produces obligations that the federal-only review misses.
8. The Compliance Calendar
The deadlines for these forms cluster on a small number of dates. A single quarter often has three or four obligations due:
January 31: 1099 forms (1099-NEC, 1099-MISC) for US payments to US contractors and 1099-K thresholds.
March 15: Form 1065 (US partnerships) and Form 1042 plus 1042-S (FDAP withholding). Extensions add six months.
April 15: Form 1120 (C-Corps), Form 1040 (individuals), Form 1120-F (foreign corporations with US office), Form 8938 (filed with the federal return), FBAR (with automatic extension to October 15).
September 15: extended deadline for Form 1065, Form 1120-S, Form 1042. Forms 5471, 5472, 8865, 8938, and 8621 follow the underlying federal return's extension.
October 15: extended deadline for individual returns, Form 1120, Form 1120-F, FBAR, and Form 926.
9. Common Compliance Failures
Treating the underlying federal return as the only obligation: the international information returns are separately filed (or attached) and have separate penalty structures. Filing Form 1120 without attached Forms 5471 or 5472 produces an incomplete return and exposes the taxpayer to the international information return penalties.
Missing FBAR for non-US residents who become US residents mid-year: the FBAR obligation kicks in when the substantial presence or green card test is met. The first FBAR for a new US resident covers all foreign accounts they had during the year, including those from before US residency.
Missing Form 5472 for foreign-owned US disregarded entities: single-member LLCs owned by a foreign person are required to file Form 5472 even if the LLC has no income. Many founders assume no income means no filing.
Missing PFIC reporting on foreign-listed funds: foreign mutual funds, ETFs, and pension fund holdings that meet PFIC tests require Form 8621. Brokerages do not always identify PFIC status on tax forms.
Late Section 1446 withholding for foreign partners: partnerships with foreign partners owe Section 1446 withholding on the foreign partner's share of ECI quarterly and report on Form 8804 plus 8805. Missing these creates partnership-level liability.
Posted originally at Taxclaim.
This post is for general informational purposes only and does not constitute professional tax, legal, or accounting advice for your specific situation. Reading this post does not create a CPA-client relationship. Tax laws are complex and subject to change. If you would like advice tailored to your situation, consult a qualified tax professional, including through the services offered on this site.

