
TaxClaim
US Tax Filing for Non-US Founders
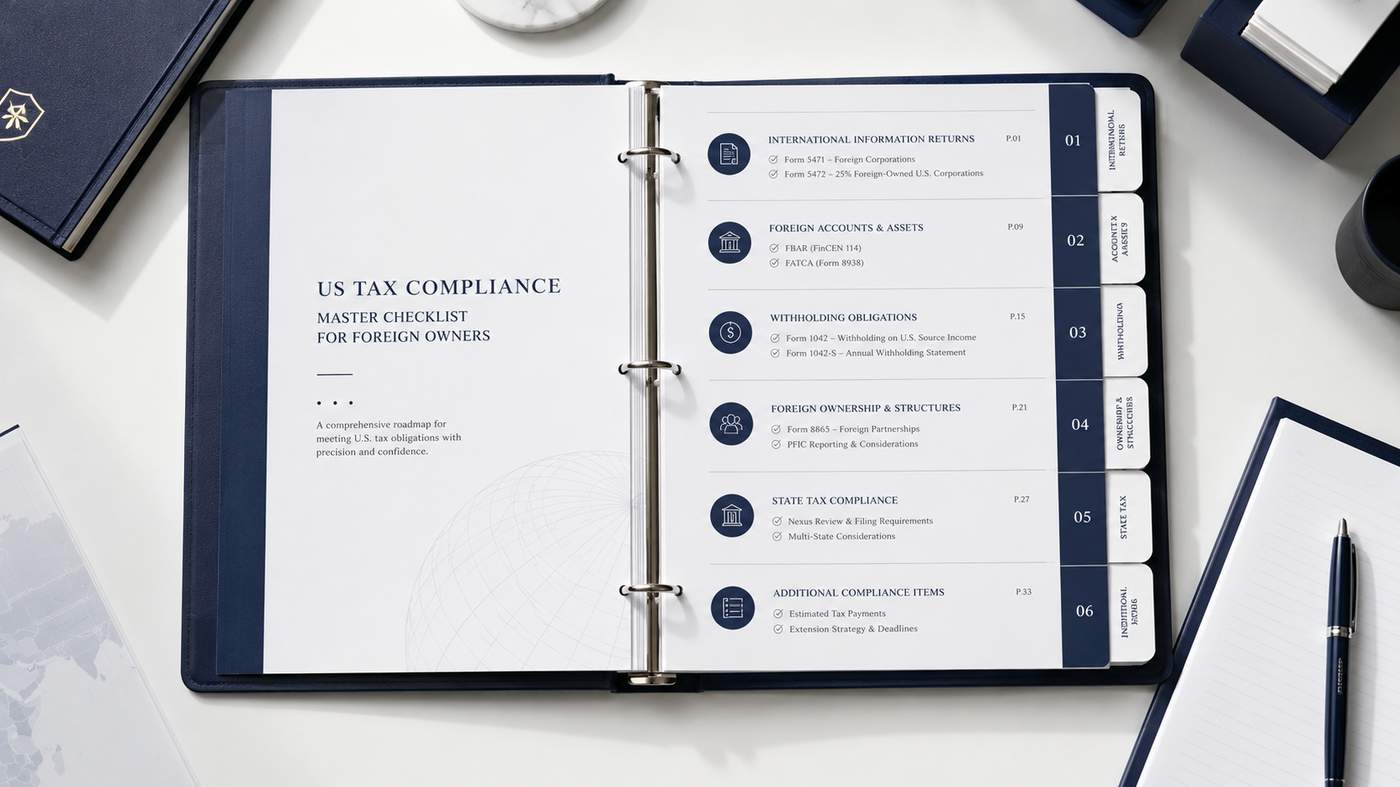
This is the master view of US tax compliance for foreign owners. The form list can feel overwhelming because the obligations layer onto each other based on what you own, where it sits, and what flows through it. The checklist below covers the core forms, the thresholds that trigger them, and how they interact so the calendar is clear before each deadline arrives.
Quick Answer
US tax compliance for foreign owners typically includes one or more of: Form 5471 for CFC ownership, Form 5472 for foreign-owned US entities with reportable transactions, Form 8865 for foreign partnerships, Form 8938 and FBAR for foreign financial assets above thresholds, Form 1042 plus 1042-S for US-source income paid to foreign persons, and state tax filings for any state with nexus. The exact combination depends on entity structure, ownership thresholds, and activity.
1. The Entity-Level Forms
These forms are filed by the US-side entity or by the controlling US shareholder, depending on entity type.
Form 1120 or Form 1065 are the underlying federal returns. Foreign-owned US entities still file the standard forms; the international information returns are attached. Our post on do foreign-owned US entities pay US tax covers the substantive tax positions that produce the numbers on these returns.
Form 1120: filed by US C-Corporations including foreign-owned ones, by April 15. Reports US-source and ECI on a worldwide basis for the corporation. Extensions to October 15 via Form 7004.
Form 1065: filed by US partnerships including foreign-owned ones, by March 15. Issues K-1s to partners. Extensions to September 15.
Form 1120-F: filed by foreign corporations with US-source income or US trade or business activity, by April 15 (June 15 if no US office). Reports ECI and FDAP.
2. Form 5472 for Foreign-Owned US LLCs and Corporations
Form 5472 is required for any 25%-or-more foreign-owned US corporation or any foreign-owned US disregarded entity (single-member LLC) that had reportable transactions with related parties during the year.
Reportable transactions: include capital contributions, loans, royalties, services, sales, rents, and most movements of value between the US entity and any related foreign party.
Filing requirement: one form per related foreign party. A US LLC owned by a single foreign owner who also lent the LLC money files at least one Form 5472, and may file more if multiple related parties had transactions.
Penalty: $25,000 per Form 5472 per year for non-filing. Continuation penalty up to $25,000 per 30-day period after IRS notice.
Our standalone post on Form 5472 filing requirements covers the related-party definition, reportable transactions, and the proforma 1120 requirement for disregarded entities.
3. Form 5471 for Controlled Foreign Corporations
Form 5471 is filed by US persons who control or hold significant interests in foreign corporations classified as CFCs. The form has multiple categories with different thresholds and information requirements.
Categories 1 through 5: covering different ownership levels and transaction types. Category 4 (control of a CFC during the year) and Category 5 (10%+ ownership of a CFC) are the most common for foreign founders with US operations.
Filing penalty: $10,000 per form per year base penalty under IRC Section 6038(b), with continuation penalty up to $50,000.
Statute of limitations: suspended on related items until the form is filed under IRC Section 6501(c)(8).
Coordination with GILTI and Subpart F: Form 5471 is the source of the inclusions reported on Form 8992 (GILTI) and the Subpart F schedules.
4. Form 8865 for Foreign Partnerships
Form 8865 is filed by US persons holding interests in foreign partnerships under IRC Sections 6038, 6038B, and 6046A. Four filing categories cover control, 10%+ ownership in US-controlled partnerships, contributions, and reportable changes.
Our standalone post on Form 8865 for foreign partnerships covers the four filing categories, the schedules required, and the catch-up procedures for prior-year gaps.
5. The Foreign Asset Reporting Forms
Form 8938: specified foreign financial assets above thresholds. For US residents, $50,000 end of year or $75,000 anytime ($100,000/$150,000 joint). For US non-residents, much higher thresholds. Filed with the federal return.
FBAR (FinCEN 114): foreign financial accounts above $10,000 in aggregate at any time during the year. Filed separately on the FinCEN site, due April 15 with automatic extension to October 15. Penalty $10,000 per non-willful violation, much higher for willful.
Form 8621: PFIC holdings, filed annually for each PFIC under IRC Section 1298(f). De minimis exception under Treasury Regulation 1.1298-1(c) for small holdings. No standalone monetary penalty but statute suspension under IRC Section 6501(c)(8).
Foreign-owner compliance gets complex fast. Most foreign founders need at least three of these forms in their first year of US operations. An international tax review maps the obligations to the structure.
6. Withholding Forms for US-Source Payments
If the foreign-owned US entity makes payments to foreign persons, withholding applies under IRC Sections 1441 and 1442 for FDAP income and Section 1445 for US real property dispositions.
Form 1042: annual return reporting amounts withheld on FDAP payments to foreign persons. Filed by the withholding agent by March 15, with extension to September 15.
Form 1042-S: issued to each foreign recipient of US-source income, summarizing the income and tax withheld. Filed with the IRS by March 15 and provided to the recipient by March 15.
Form W-8 series: received from foreign payees to certify non-US status and claim treaty benefits. The withholding agent retains these in records, does not file with the IRS.
Form 8804 and 8805: for partnerships with foreign partners and ECI, reporting Section 1446 withholding on the foreign partner's share of partnership ECI.
If your US entity has paid US-source income to foreign owners or contractors, the withholding mechanics, treaty rate reductions, and the $250 per-form penalty structure on Form 1042-S are summarized in our standalone post on FDAP withholding.
7. State Tax Compliance
State tax obligations apply alongside federal compliance and follow each state's own nexus and filing rules. Foreign owners often miss state filings because they think federal compliance is enough.
State income tax in any state with nexus from operations, employees, or significant inventory presence
State sales tax and use tax in states with economic nexus thresholds, typically based on revenue or transaction count
State franchise or annual report fees in formation states (Delaware franchise tax for entities formed in Delaware, California $800 minimum tax for entities doing business in California)
State-by-state nexus rules and the specific obligations in high-volume states are covered in our state tax compliance post for foreign-owned LLCs. The state analysis runs separately from federal and often produces obligations that the federal-only review misses.
8. The Compliance Calendar
The deadlines for these forms cluster on a small number of dates. A single quarter often has three or four obligations due:
January 31: 1099 forms (1099-NEC, 1099-MISC) for US payments to US contractors and 1099-K thresholds.
March 15: Form 1065 (US partnerships) and Form 1042 plus 1042-S (FDAP withholding). Extensions add six months.
April 15: Form 1120 (C-Corps), Form 1040 (individuals), Form 1120-F (foreign corporations with US office), Form 8938 (filed with the federal return), FBAR (with automatic extension to October 15).
September 15: extended deadline for Form 1065, Form 1120-S, Form 1042. Forms 5471, 5472, 8865, 8938, and 8621 follow the underlying federal return's extension.
October 15: extended deadline for individual returns, Form 1120, Form 1120-F, FBAR, and Form 926.
9. Common Compliance Failures
Treating the underlying federal return as the only obligation: the international information returns are separately filed (or attached) and have separate penalty structures. Filing Form 1120 without attached Forms 5471 or 5472 produces an incomplete return and exposes the taxpayer to the international information return penalties.
Missing FBAR for non-US residents who become US residents mid-year: the FBAR obligation kicks in when the substantial presence or green card test is met. The first FBAR for a new US resident covers all foreign accounts they had during the year, including those from before US residency.
Missing Form 5472 for foreign-owned US disregarded entities: single-member LLCs owned by a foreign person are required to file Form 5472 even if the LLC has no income. Many founders assume no income means no filing.
Missing PFIC reporting on foreign-listed funds: foreign mutual funds, ETFs, and pension fund holdings that meet PFIC tests require Form 8621. Brokerages do not always identify PFIC status on tax forms.
Late Section 1446 withholding for foreign partners: partnerships with foreign partners owe Section 1446 withholding on the foreign partner's share of ECI quarterly and report on Form 8804 plus 8805. Missing these creates partnership-level liability.
Posted originally at Taxclaim.
This post is for general informational purposes only and does not constitute professional tax, legal, or accounting advice for your specific situation. Reading this post does not create a CPA-client relationship. Tax laws are complex and subject to change. If you would like advice tailored to your situation, consult a qualified tax professional, including through the services offered on this site.

If you own a US entity as a non-US resident, getting money from the entity to yourself is rarely as simple as a bank transfer. Different routes produce different tax outcomes, and routes that look interchangeable produce different filing obligations. The wrong choice creates US tax exposure that the right choice avoids.
Quick Answer
The five mechanisms are: (1) owner distribution from a pass-through, (2) salary as a W-2 employee, (3) contractor payment via 1099, (4) dividend from a C-Corp, (5) royalty for licensed intellectual property. Distribution and dividend depend on entity structure. Salary and 1099 depend on where the work is performed. Royalty applies only when the entity is licensing IP from you.

1. The Threshold Question
Before any payment is made, three facts decide the available options.
Entity structure: disregarded LLC, partnership LLC, S-Corp (not available to non-residents), or C-Corp. The structure determines whether a payment is a distribution of the owner's own income or a separate transaction.
Where the work is performed: services performed inside the US generally produce US-source income for the person performing them. Services performed entirely outside the US generally do not. The location of the work, not the location of the payer, drives US tax treatment for compensation.
US tax residency status: non-resident aliens are taxed only on US-source income. Resident aliens are taxed on worldwide income. The substantial presence test can convert a non-resident to a resident without immigration changes.
If you have not yet confirmed your residency status or your entity classification, those questions come first. Our LLC Taxation guide covers the four classification options and what each means for owner payments.
2. Owner Distribution from a Pass-Through Entity
This is the most common mechanism for foreign-owned LLCs.
A disregarded single-member LLC is transparent for US income tax. Money in the LLC's bank account is already considered the owner's money. Transferring it to a personal account is not technically a payment. It is the owner withdrawing their own funds. No US payroll, no withholding, no separate income tax event at the moment of transfer.
The income tax obligation arises from the underlying activity, not from the distribution. If the LLC's activity produced ECI, the owner files Form 1040-NR and pays US tax at graduated rates regardless of whether the money was distributed. If the activity did not produce US-source income, distribution does not create one.
For a multi-member partnership LLC, the same principle applies but with a complication. Each owner is taxed on their allocated share of the LLC's income reported on Schedule K-1, whether or not the income was distributed. Distributions are not separate income events. Distributions in excess of the owner's basis can produce gain recognition, which is a separate analysis.
3. Salary as a W-2 Employee
Salary requires the owner to be a W-2 employee of the US entity, with all the obligations that creates: payroll tax registration in the relevant states, FICA and Medicare withholding, federal and state income tax withholding, quarterly Form 941, year-end W-2 issuance.
For a non-resident owner, salary creates a fundamental issue. Compensation for services performed in the US is generally US-source income, taxed as ECI on Form 1040-NR at graduated rates. Compensation for services performed outside the US is generally foreign-source and may not be subject to US tax at all.
If the owner is performing services in the US under appropriate work authorization, salary is straightforward but expensive. If services are performed entirely outside the US, paying salary through US payroll often creates US-source income that would not otherwise exist, and creates compliance costs that produce no business benefit.
S-Corp election is not available to non-resident owners. The reasonable salary requirement that applies to S-Corp shareholders does not apply to non-resident-owned entities.
4. Contractor Payment via Form 1099
If the owner provides services to the US entity from outside the US and does not want to be a US employee, the contractor route is often the cleanest.
The mechanic: the owner provides Form W-8BEN to the entity confirming non-resident status. The entity pays the owner as a foreign contractor. If services are performed entirely outside the US, the income is foreign-source and not subject to US withholding. If services are performed in the US, US-source rules apply and the income may be ECI subject to graduated tax.
Form 1042-S, not Form 1099, is the correct reporting form for payments to foreign contractors. The W-8BEN has to be on file before payment for the foreign-source treatment to apply. Without it, the entity is required to withhold at default rates on the assumption that the income is US-source.
This route requires careful documentation of where the work was performed. Travel days in the US during which work was conducted can convert otherwise foreign-source compensation into US-source income on a partial basis.
If you are setting up the payment structure for the first time and want to make sure the route fits your entity and residency, an international tax review runs the analysis before payments begin.
5. Dividend from a C-Corp
Dividends are available only when the entity is a C-Corp. They are not a pass-through mechanism.
A C-Corp pays US federal corporate income tax on its income at 21%. After-tax profits can be distributed to shareholders as dividends. For a non-resident shareholder, dividends are FDAP income subject to 30% US withholding at source, unless reduced by an applicable income tax treaty.
Most US treaties reduce the dividend rate to 15% for portfolio shareholders and lower (often 5% to 10%) for substantial corporate shareholders meeting an ownership threshold. Reduced rates require Form W-8BEN-E on file with the corporation before the dividend is paid.
The combined burden of corporate tax plus dividend withholding is what makes the C-Corp structure expensive for owners who plan to extract profits. For owners reinvesting profits in the business or building toward an exit through a stock sale rather than ongoing distributions, the structure works differently.
Our comparison of Delaware C-Corp vs LLC for foreign founders covers when each structure makes sense, including how owner payments factor into the choice.
6. Royalty for Licensed Intellectual Property
If the owner personally holds IP (software, trademarks, patents, copyrights) and licenses it to the US entity, the entity can pay royalties for the license.
Royalties are FDAP income subject to 30% US withholding at source by default, often reduced under a tax treaty. Withholding rates for royalties vary more than dividend rates by treaty and by the type of royalty (industrial, copyright, know-how).
This route requires a real licensing arrangement with proper documentation: a written license agreement at arm's-length terms, IP that genuinely exists and was developed by the owner, royalty rates supported by transfer pricing analysis. The IRS scrutinizes royalty arrangements between related parties closely. A bare assertion that the owner holds IP, without underlying substance, does not produce a defensible position.
Where it works: the owner developed the underlying IP before the US entity was formed and has documented ownership. Where it does not work: the IP was developed inside the US entity using its resources, then transferred to the owner without consideration, then licensed back.
7. Side-by-Side Comparison
The mechanics of each route at a glance:

8. Common Mistakes
Setting up US payroll for self when work is performed abroad: creates US-source ECI that would not otherwise exist. Adds compliance costs without business benefit.
Treating distributions as deductible business expenses: owner distributions are not deductions. They are after-tax movements of the owner's own funds.
Not getting W-8BEN on file before contractor payments: default 30% withholding applies until the form is on file. Recovery requires filing a return and waiting six months or longer for refund.
Claiming royalties without underlying IP substance: the IRS treats sham royalty arrangements as disguised distributions. Penalties can include the disallowed deduction at the entity level plus accuracy-related penalties.
Mixing routes within the same year without clean documentation: an owner who took some payments as distributions and others as contractor fees needs documentation supporting why each was treated as it was. Inconsistent characterization without basis invites IRS reclassification.
If you are still working out whether your activity creates ECI in the first place, our post on ECI vs FDAP covers the framework that determines how each payment route is taxed.
Posted originally at TaxClaim.
This post is for general informational purposes only and does not constitute professional tax, legal, or accounting advice for your specific situation. Reading this post does not create a CPA-client relationship. Tax laws are complex and subject to change. If you would like advice tailored to your situation, consult a qualified tax professional, including through the services offered on this site.
Whether you owe US tax on income earned outside the United States depends entirely on one question: are you a US tax resident or a non-resident alien? The answer is not always obvious, and the IRS has specific rules for making that determination.
Getting it wrong in either direction creates problems. Residents who file as non-residents underreport worldwide income. Non-residents who file as residents claim credits and deductions they are not entitled to. Both create audit exposure.
This post covers how the IRS determines your status, what each classification means for your tax obligations, and what happens in the year you change from one to the other.

This applies to you if you are:
A foreign founder with a US entity who spends time in the United States
On an H-1B, L-1, F-1, O-1, or similar visa
A remote worker or digital nomad splitting time between countries
Moving into or out of the United States during the year
A green card holder who has been living outside the US
The Two Tests That Determine US Tax Residency
The IRS uses two tests to determine whether a non-US citizen is a US tax resident. Meeting either one makes you a resident alien for federal tax purposes.
The Green Card Test
If you are a lawful permanent resident of the United States at any point during the calendar year, you are generally treated as a US tax resident for that year, subject to start and end date rules in the year your status begins or ends. It does not matter how many days you were physically present in the US. It does not matter whether you lived primarily abroad. The green card alone is sufficient.
Residency under the green card test ends only when your status is officially revoked or abandoned. Letting a green card expire without formally abandoning it does not end your US tax residency. The IRS and USCIS operate on different tracks. You can lose your immigration status while still being treated as a tax resident.
If you do not have a green card, the IRS counts your days in the United States over a three-year rolling period. You are a US tax resident for the current year if you meet both of the following:
At least 31 days present in the current year
A total of 183 days or more under the weighted formula
Not every day counts equally. Days present as a diplomat, certain government employees, teachers or trainees on J or Q visas, students on F, J, M, or Q visas, or a professional athlete competing in a charitable event are generally excluded. Days you were unable to leave due to a medical condition that developed while you were present in the US are also excluded.
How to Calculate Your Substantial Presence Days
The 183-day threshold is not a simple count of days in the current year. The IRS uses a weighted formula across three years.
Step 1: Count every qualifying day you were present in the US during the current year. That number counts in full.
Step 2: Count your qualifying days from the prior year and multiply by one-third.
Step 3: Count your qualifying days from the year before that and multiply by one-sixth.
Step 4: Add the three figures together. If the total is 183 or more, and you were present for at least 31 days in the current year, you meet the substantial presence test.
Example: 120 days this year, 90 days last year, 60 days two years ago. The calculation is 120 + 30 + 10 = 160. That is below 183, so the test is not met for the current year.
The weighted formula is why someone who has been splitting their time across multiple countries for several years can trigger US residency without ever spending more than four months in the US in a single year. The prior years follow you.
What US Tax Residency Actually Means

If You Are a Resident Alien
You are taxed the same way a US citizen is taxed. That means worldwide income, from every country, from every source, is subject to US federal income tax. Your salary from a foreign employer, your rental income from property abroad, your dividends from a foreign brokerage account: all of it goes on your US return.
You file Form 1040. Foreign tax credits and the foreign earned income exclusion may be available depending on your situation, but the obligation to report starts with all income, everywhere.
You may also have additional reporting obligations. If you have financial accounts outside the United States with aggregate balances exceeding $10,000 at any point during the year, FBAR applies. The FBAR deadline is April 15, with an automatic extension to October 15. If you hold specified foreign financial assets above certain thresholds, Form 8938 may also be required. These are separate from the income tax return and carry their own penalties.
If You Are a Non-Resident Alien
You are taxed only on US-source income. Income earned entirely outside the United States, with no US connection, is generally outside the reach of US federal income tax.
US-source income for a non-resident falls into two categories. The first is income effectively connected to a US trade or business, known as ECI, which is taxed at graduated rates on net income after deductions. The second is fixed, determinable, annual, or periodical income from US sources, known as FDAP, which is generally subject to 30% withholding on the gross amount, unless a tax treaty reduces that rate. Our post on how ECI and FDAP work for foreign-owned US entities covers both categories in full.
Non-residents file Form 1040-NR. Filing the wrong form is not a minor clerical issue. The forms produce different results.
The Closer Connection Exception
If you meet the substantial presence test but spent fewer than 183 days in the US during the current year, you may be able to claim a closer connection to a foreign country and avoid US tax residency for that year.
To qualify, you must have maintained a tax home in a foreign country during the year and had a closer connection to that country than to the United States. The IRS looks at where your permanent home is, where your family lives, where your personal belongings are, where you hold licenses and bank accounts, and where you conduct your business. You file Form 8840 to make this claim. The exception only applies if Form 8840 is filed on time.
The closer connection exception is not available if you have applied for adjustment of status or taken affirmative steps toward obtaining lawful permanent residency at any point during the year, such as filing an I-485 or similar application.
A note for digital nomads and remote tech workers:
Many remote workers assume that because their employer is not a US company, their days in the United States do not count toward residency. That is not how the IRS sees it. The substantial presence test looks at physical presence, not the location of your employer or the source of your paycheck.
If you spend four months a year in the US while working remotely for a company based abroad, those days count. Add the weighted prior-year days, and you may cross 183 without realizing it. In practice, we often see this situation arise when someone has been traveling in and out of the US for a few years without tracking their days. By year three, the prior years have already done most of the counting.
The Closer Connection Exception through Form 8840 is often the primary planning tool in this situation. Whether it applies to your specific circumstances depends on the facts, and those facts matter.
Tax Treaties and Residency Tiebreakers
If you are a tax resident of both the United States and a country with which the US has an income tax treaty, the treaty's tiebreaker rules may determine where you are treated as a resident for tax purposes.
Treaty tiebreakers generally look at where you have a permanent home, where your personal and economic relations are closer, where you have a habitual abode, and finally your nationality. These are applied in sequence, stopping at the first factor that produces a clear answer.
A successful treaty tiebreaker claim does not eliminate your US filing obligation. It limits what income the US can tax. You are still required to file a US return, disclose the treaty position, and report the income that remains taxable in the United States. The position is taken on a return, not simply declared.
Treaty benefits require proper documentation, timely disclosure, and in some cases specific forms. Assuming the benefit applies without taking the required steps means the IRS is not bound by it.
Dual-Status Tax Years
The year you arrive in the United States and become a resident is not a full resident year. Neither is the year you leave. These are dual-status years, and they are handled differently.
In a dual-status year, you are treated as a non-resident alien for the part of the year before you became a resident, and as a resident alien for the part after. Income is reported based on which status applied when it was earned.
The filing mechanics depend on your status at year-end. If you are a resident at year-end, you file Form 1040 as the primary return and attach Form 1040-NR as a statement covering the non-resident portion. If you are a non-resident at year-end, Form 1040-NR is the primary return and Form 1040 is attached as the statement. The two are not filed separately in either case.
Dual-status filers face restrictions that full-year residents do not. You generally cannot use the standard deduction. You cannot file a joint return unless your spouse makes a specific election under IRC Section 6013(g) to be treated as a full-year resident. That election allows you to file jointly and claim the standard deduction, but it also brings your spouse's worldwide income into the US return for the full year. The trade-off matters, and it should be evaluated before the election is made. Certain credits are also off the table for dual-status filers who do not make that election.
The dual-status year is where the most common mistakes happen. Worldwide income gets included in the non-resident portion. The wrong form gets filed as the primary return. The standard deduction gets claimed when it should not be. Each of these creates an amended return situation at best, and an examination at worst.
If you are on an H-1B, L-1, or O-1 visa and changed your status during the year, or if you received a green card mid-year, you very likely had a dual-status year that requires a specific filing approach.
First-Year Election
If you did not meet the substantial presence test for the current year but will meet it for the following year, and you were present in the US for at least 31 consecutive days during the current year, you may be able to elect to be treated as a resident for part of the current year.
To qualify, you must also have been present in the US for at least 75% of the days from the first day of that 31-consecutive-day period through December 31 of the current year. Days of absence of up to 5 per month are counted as days of presence for purposes of that 75% calculation. The residency starting date under this election is the first day of that 31-consecutive-day period.
Example: You arrive June 1 and remain in the US for the rest of the year with only brief absences. June 1 through December 31 is 214 days. If you were present for at least 161 of those days (75%), and you will meet the substantial presence test for the following year, you can elect to be treated as a US resident from June 1 of the current year. Your filing for that year would cover the resident period only, not the full year.
This is an affirmative election made on a timely filed return, including extensions. Missing the deadline means the election is not available for that year.
Whether the election is beneficial depends on your specific income and filing situation. It is not always advantageous.
State Tax Residency Is a Separate Question
Federal tax residency and state tax residency are not the same determination. Each state has its own rules.
Most states use a domicile test, a statutory residency test based on days present and maintaining a permanent place of abode, or both. A person who is a non-resident alien for federal purposes may still be a state tax resident if they spent enough days in a particular state and maintained a home there.
California and New York are the most aggressive in asserting residency. Simply leaving the state does not automatically end California or New York residency for state tax purposes. If you are moving in or out of a high-tax state in the same year you are changing your federal residency status, those are two separate analyses with potentially different answers.
Residency and Ownership of US Entities
Your residency status directly affects your obligations when you own a US entity.
If you are a non-resident alien and you own a US LLC, that LLC is treated as a foreign-owned disregarded entity, which triggers a Form 5472 filing obligation from the year of formation regardless of whether it has taxable income. The penalty starts at $25,000 per year. Our complete guide to Form 5472 for foreign-owned US entities covers the filing requirements, what transactions need to be reported, and what happens if filings are missed.
If you are a US tax resident and you own shares in a foreign corporation, Form 5471 may be required depending on your ownership percentage and level of control. The penalty starts at $10,000 per form per year, and missing it keeps your entire return permanently open to IRS audit with no time limit. Our post on Form 5471 filing requirements covers who has to file and which category applies.
Changing your residency status without reviewing your entity filing obligations is one of the most common gaps we see.
Expatriation and Exit Tax
If you give up your US citizenship or long-term permanent residency, the US imposes an exit tax on certain individuals.
A long-term resident is someone who has held a green card for at least 8 of the past 15 years. If you are a long-term resident formally abandoning your green card, or a US citizen renouncing citizenship, you are a covered expatriate if you meet any of the following thresholds for 2026: average net annual US income tax liability over the past 5 years exceeds $211,000, net worth on the expatriation date is $2 million or more (including worldwide assets), or you cannot certify compliance with all US tax obligations for the prior 5 years.
Covered expatriates are treated as if they sold all of their assets at fair market value on the day before expatriation. The 2026 exclusion amount on mark-to-market gains is $910,000. Gains above that are taxed in the year of departure. Certain deferred compensation, interests in non-grantor trusts, and specified tax-deferred accounts are also affected.
Form 8854 is required in the year of expatriation. Failure to file it means you are treated as a covered expatriate regardless of whether you actually meet the thresholds. The numbers above are adjusted annually. What applies to your year of departure requires a current-year review.
Common Residency Mistakes and What They Lead To
Filing Form 1040 as a non-resident. Non-residents file Form 1040-NR. Using the wrong form can result in the standard deduction being applied incorrectly, worldwide income being excluded when it should be included, and credits being claimed that have residency requirements attached.
Assuming the green card is what matters for immigration, not taxes. Many green card holders who have lived abroad for years believe they are not US tax residents because they do not live in the US. Until the green card is formally abandoned through Form I-407 and a proper final return is filed, the filing obligation continues.
Counting days incorrectly under substantial presence. The weighted formula catches people who split their time between countries. They count 31 days in the current year and assume they do not meet the test, without running the full three-year calculation.
Treating treaty positions as automatic. A tax treaty can limit US tax obligations, but claiming the benefit requires proper disclosure, timely filing, and documentation. Assuming the benefit applies without taking the required steps means the IRS is not bound by it.
Missing the dual-status year entirely. People in transition years often file either a full-year Form 1040 or a full-year Form 1040-NR when neither is correct. This is not what most tax software defaults to, and it is not intuitive.
Each of these situations has a specific resolution path. What that looks like depends on the facts, how many years are involved, and whether the IRS has already made contact. If you are trying to sort out prior years or a current filing, start here.
This post is for general informational purposes only and does not constitute professional tax, legal, or accounting advice for your specific situation. Reading this post does not create a CPA-client relationship. Tax laws are complex and subject to change. If you would like advice tailored to your situation, consult a qualified tax professional, including through the services offered on this site.
If you own a US LLC or corporation as a non-US resident, the IRS expects you to file even if your business had no income during the year. The penalty for missing the most basic reporting requirement starts at $25,000 per year.
The US taxes foreign owned entities based on whether income is tied to an active US business or is passive US-source income. Your tax rate, withholding, and filing obligations all follow from that classification.
1. The Two Income Categories That Determine Everything
The IRS divides US-source income into two categories. Every dollar your entity earns falls into one of them.
Effectively Connected Income (ECI): Income earned from actively conducting a trade or business in the United States. Taxed on a net basis after allowable deductions at standard graduated rates.
Fixed, Determinable, Annual, or Periodical income (FDAP): Passive US-source income such as dividends, interest, rents, and royalties. Taxed on a gross basis at a 30% withholding rate, which may be reduced under an applicable tax treaty.
The distinction matters more than most foreign owners realize. ECI and FDAP are reported on different forms, taxed differently, and subject to entirely different withholding rules. Misclassifying your income leads to incorrect withholding and, in many cases, penalties.
2. How ECI Is Taxed
If your entity is conducting a US trade or business, any income connected to that activity is ECI. A foreign owned corporation with ECI files a US corporate return and pays tax on net income after deductions.
For foreign owned LLCs, the tax treatment depends on how the LLC is classified. A single member LLC owned by a non-US resident is treated as a disregarded entity by default, which means the income flows directly to you as the owner. If you are unsure what disregarded entity status means for your situation, start with our post on LLC taxation and how to tax your LLC.
Whether your specific activity rises to the level of a US trade or business is a facts-and-circumstances determination. Getting it wrong affects every return you file going forward.
A foreign owned C-Corporation has a different starting point entirely. It files Form 1120 and pays US corporate tax as a separate taxable entity, regardless of whether income is ECI or FDAP. The filing obligation exists from the year of incorporation, independent of activity or income level.
3. How FDAP Income Is Taxed
FDAP applies even if you have no active US business presence. If your entity is receiving passive income from a US source, that income is subject to US withholding tax.
Common FDAP income types include:
Dividends: Paid by US corporations to foreign shareholders
Interest: From US banks or US-based borrowers
Rental income: From US real property, when not treated as ECI
Royalties: For the use of intellectual property within the United States
The withholding obligation falls on the US payor. They withhold 30% from the gross amount before payment. No deductions apply.
If you are receiving payments from US sources and are unsure how they are being classified, that is worth confirming before your next filing. Incorrect withholding by the payor does not eliminate your liability.
4. Tax Treaties and How They Affect Withholding
If your country of residence has a tax treaty with the United States, you may be able to reduce or eliminate the 30% withholding rate on FDAP income. The benefits vary by income type and by treaty.
Treaty benefits are not automatic. Eligibility depends on the type of income, the structure of your entity, and whether you meet the conditions set out in the treaty. Most US tax treaties also include provisions that can restrict access to benefits based on ownership and activity requirements.
Ensure that you confirm treaty applicability before your first payment is received. The documentation requirements are specific, and retroactive claims are limited.
5. The Branch Profits Tax
If you operate in the US through a branch of a foreign corporation rather than a separately incorporated US entity, there is an additional layer of tax that applies on top of regular income tax.
The branch profits tax is designed to put branch operations on equal footing with foreign corporations that operate through a US subsidiary. The right structure between a branch and a US entity depends on your country of residence, your treaty position, and your long term plans. The consequences of choosing the wrong structure are difficult to reverse.
6. Form 5472: Where Most Penalties Arise
Form 5472 is required for any US corporation that is at least 25% foreign owned, and for foreign owned single member LLCs treated as disregarded entities. It is used to report transactions between the US entity and its foreign owners or related parties. It is not a tax payment form. It is a disclosure form.
The penalty applies even if your entity had no income or activity during the year. More significantly, the statute of limitations for Form 5472 stays open indefinitely until the form is filed. The IRS can assess the penalty years after the original due date, with no time restriction. The three-year audit window that protects most filers never starts until the form is actually filed.
We cover the full filing requirements, deadlines, and penalty rules in our post on Form 5472 filing requirements for foreign owned US entities.
Transactions you are required to report include:
Capital contributions: Money transferred from you as the foreign owner into the US entity
Distributions: Payments made from the US entity back to you
Loans: Any lending between the US entity and the foreign owner or related parties
Non-cash transfers: Property, equipment, or intellectual property moved between related parties
Services: Work performed by you for the US entity, or by the US entity for you
For broader recordkeeping practices, our Compliance 101 guide covers what ongoing compliance looks like once your entity is active.
7. State Tax Is a Separate Obligation
Federal compliance covers only part of what you owe. Most US states impose their own income and franchise taxes, and if your entity is registered or doing business in a state, those obligations apply separately from your federal requirements.
States vary in how they define nexus, which is the minimum connection that triggers a filing obligation. Common nexus triggers include:
Physical presence: An office, warehouse, employees, or inventory located in the state
Economic nexus: Exceeding a revenue or transaction threshold from sales to customers in that state
Registration: Being formally registered as a foreign entity doing business in that state
Sales tax and use tax are a separate compliance track from income tax. Our post on sales tax vs. use tax covers how these rules apply to businesses operating across state lines.
8. What Happens When You Get It Wrong
Most foreign owners discover their US obligations after a mistake. By that point, the consequences are already in motion.
Missing Form 5472 for a single year means a $25,000 penalty with no income threshold. Misclassifying your income leads to incorrect withholding and back taxes with interest. The wrong entity structure or a missed election can lock you into an unfavorable tax position for the life of the entity. State penalties run on a separate track and do not wait for federal resolution.
Disclaimer: This post is for general informational purposes only and does not constitute professional tax, legal, or accounting advice for your specific situation. Reading this post does not create a CPA-client relationship. Tax laws are complex and subject to change. If you would like advice tailored to your situation, consult a qualified tax professional, including through the services offered on this site.
Comment